
Here’s a collection of last month’s sales data for the areas served by RMLS. I hope you find it helpful.Want to get notified of new updates by email? Click here to subscribe!Please note,

Dated: April 8 2023
Views: 126
Want to get notified of new updates by email? Click here to subscribe!
-----
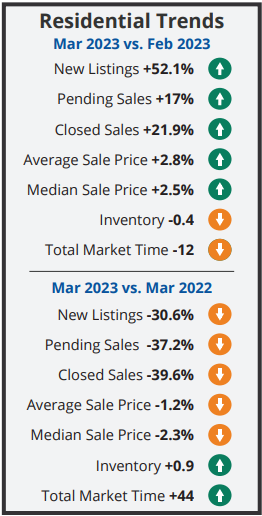
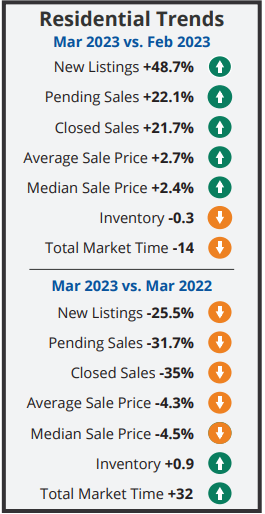
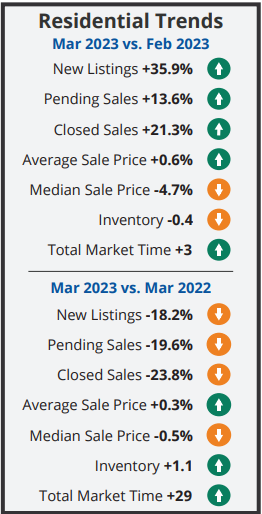
Please note, the arrows in the trends table only showcase numbers going up or down - NOT whether or not the trend is beneficial as this is determined based on perspective.
-----
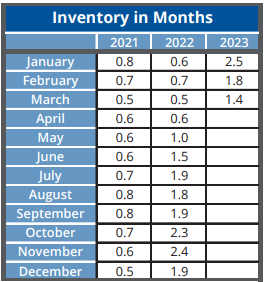
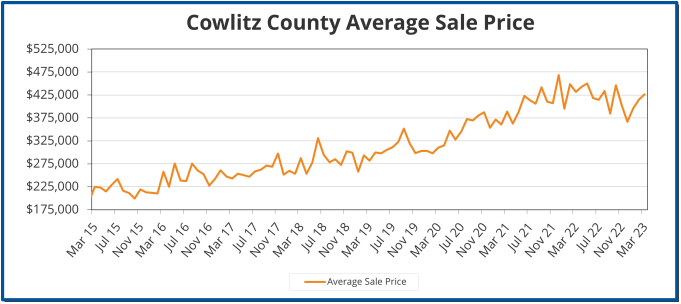
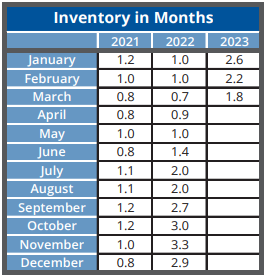
Inventory is trending down.
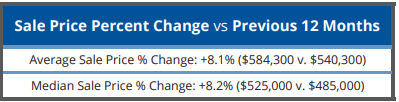
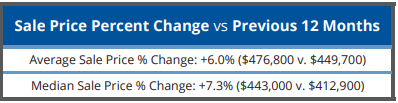
Appreciation is still up, yet lower versus last month year-over-year.
-----
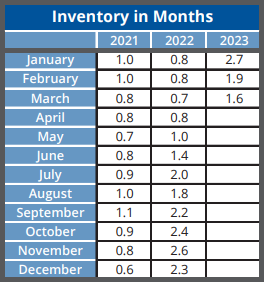
Inventory is trending down.
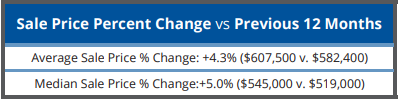
Appreciation is still up, yet lower versus last month year-over-year.
-----
Inventory is trending down.
Appreciation is still up, yet about equal versus last month year-over-year.
-----
-----
Blacknight Mortgage Report click here, February 2023. Interesting facts:
-----
Some market snapshots.
FIRST-TIME BUYER homes priced below $400,000 in SW Washington. By summertime, I doubt they will exist. Click here to see that info.
FIRST-TIME BUYER homes priced below $400,000 south of the Columbia River. Click here to see that info.
FAIRVIEW VILLAGE, WA is an anomaly in the area, holding prices higher. Click here to see the info.
LONGVIEW / KELSO area is still attractive for families looking for starter homes. Click here to see that info.
Area single family homes with at least 3 bedrooms, 1.5 baths, at least 0.75 acres, and a maximum of $850,000. Click here to see that info.
And get your home value, or the neighbor's house, instantly! Click here for that page.
Trends that I have noticed in the last few weeks & final note:
Prices are still going up. With new builds/homes, once the listing is published, price adjustments tend to go up. With resale homes, once the listing is published, price adjustments tend to go down.
Everyone keeps asking me when prices are going to crash. They aren't in my opinion. There is still so much pent up demand, of buyer's sitting on the fence, waiting for a better day in interest rates or prices. Look around. See all the mult-family building that is happening, which is seemingly filling up right away? These are future buyers. Home builders are just not keeping pace with new homes. The only thing keeping demand down right now is the rates.
The average price is up versus a few months ago, so when is the right time to buy? Right now, while the rest of the market is waiting, you or someone you know can buy a home with less competition versus a one to two years ago. But that will change as the rates come down. People will come out of the woodwork. Even the homes that are of decent quality and being listed below comps, these are obtaining multiple offers.
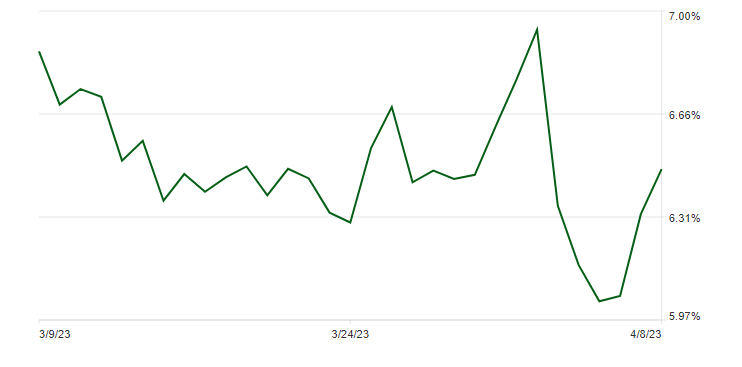
We Realtors do not know when it will happen, but if and when interest rates drop to below 5% it will be back to bidding wars.
The four basic compenents of buying a house are 1) income (hardest to control), 2) savings (for down payment and closing costs), 3) household cashflow aka debt-to-income ratio (easier to control), and 4) credit rating (easier to control).
Most conversations I am having now are centered on encouraging people to improve their household cashflow and keeping their debt-to-income ratio lower. If someone has a large income, some savings, ok credit, yet if your debt-to-income ratio is too high, this kills the availability of a good rate for a loan.
-----
Let me know how I can help you!?
Want to get notified of new updates by email? Click here to receive notifications.
Hello, I'm Steve Milford, and I look forward to meeting and working with you. My perspective is a little bit different. I didn't become a Realtor for a job, I starting this journey because I like to f....
Here’s a collection of last month’s sales data for the areas served by RMLS. I hope you find it helpful.Want to get notified of new updates by email? Click here to subscribe!Please note,
Here’s a collection of last month’s sales data for the areas served by RMLS. I hope you find it helpful.Want to get notified of new updates by email? Click here to subscribe!Please note,
January's Jobs Report warrants a closer look, inflation data was encouraging, and existing home sales slowed to start the year. Here's a look at the key highlights.Headline Jobs Number Strong, But
Here’s a collection of last month’s sales data for the areas served by RMLS. I hope you find it helpful.Want to get notified of new updates by email? Click here to subscribe!Please note,
 All information provided is deemed reliable but is not guaranteed and should be independently verified. IDX information is provided exclusively for consumers' personal, non-commercial use, that it may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing, and that the data is deemed reliable but is not guaranteed accurate by RMLSTM.
The content relating to real estate for sale on this web site comes in part from the IDX program of the RMLSTM of Portland, Oregon. Real estate listings held by brokerage firms other than Kelly Right Real Estate are marked with the RMLSTM logo, and detailed information about these properties includes the names of the listing brokers. Listing content is copyright © 2026 RMLSTM, Portland, Oregon.
This content last updated on September 24, 2026 7:33 PM UTC at 4 AM. Some properties which appear for sale on this web site may subsequently have sold or may no longer be available.
 Southern Oregon Multiple Listing Service All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be
interested in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than Kelly Right Real Estate may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 24, 2026 8:13 PM UTC
Show More...
 All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. The data relating
to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than Kelly Right Real Estate may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 24, 2026 8:21 PM UTC
Show More...
