
Here’s a collection of last month’s sales data for the areas served by RMLS. I hope you find it helpful.Want to get notified of new updates by email? Click here to subscribe!Please note,

Dated: April 20 2024
Views: 1316
Want to get notified of new updates by email? Click here to subscribe!
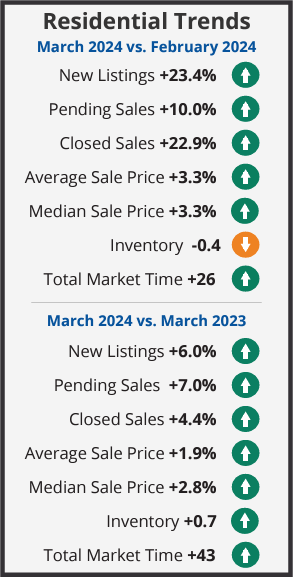
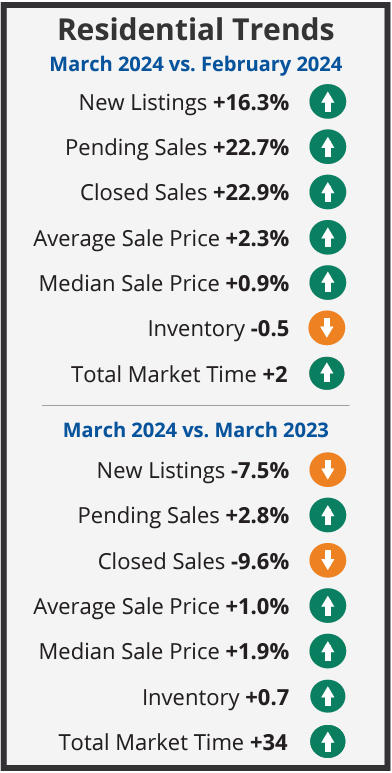
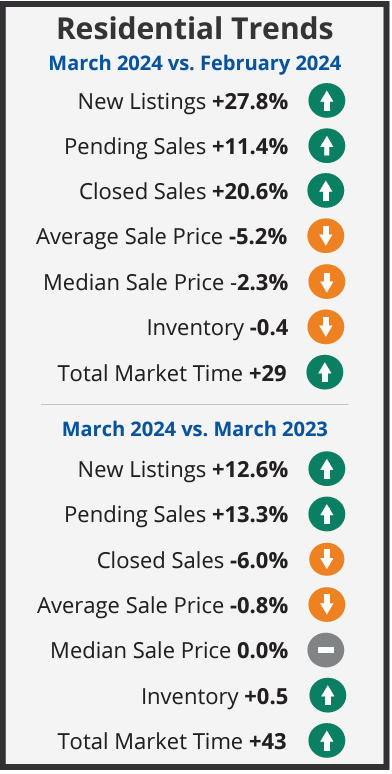
Please note, the arrows in the trends table only showcase numbers going up or down - NOT whether or not the trend is beneficial as this is determined based on perspective.
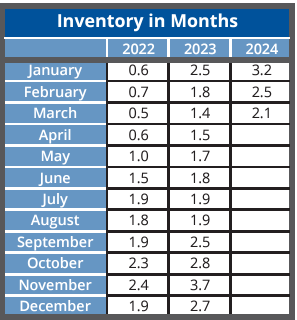
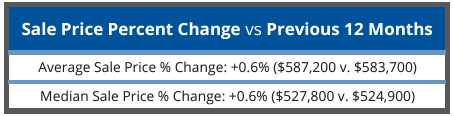
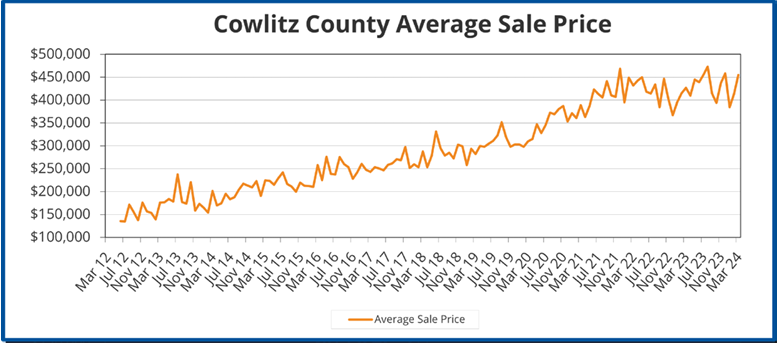
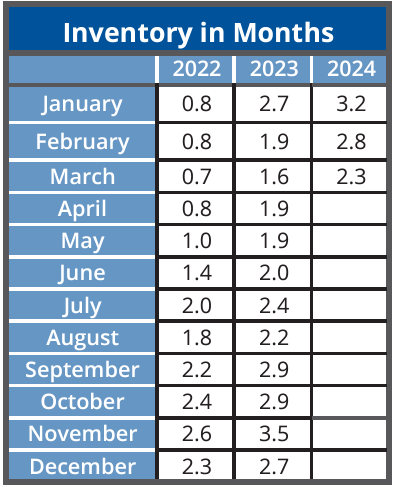
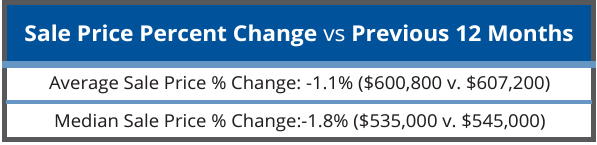
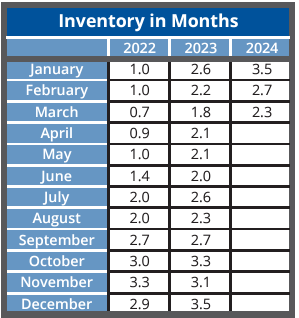
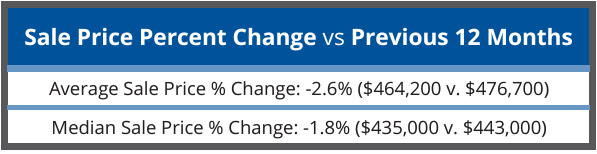
In summary, the number of listings are up, prices are up, time on the market is up, and the 12-month rolling average appreciation of prices are flat or going down.
SW Washington Report (Clark & Cowlitz) (read report here)
-----
Some market snapshots:
Homes priced BELOW $400,000 in SW Washington. Click here to see that info.
Homes priced BELOW $400,000 south of the Columbia River. Click here to see that info.
FAIRVIEW VILLAGE, WA is an anomaly in the area, holding prices higher. This is a 55+ community. Click here to see the info.
LONGVIEW / KELSO area is still attractive for families looking for starter homes. Click here to see that info.
PORTLAND-METRO & SW WASHINGTON single-family homes with at least 3 bedrooms, 1.5 baths, at least 0.75 acres, and a maximum of $850,000. Click here to see that info.
To get your home value and a market report sent to your email each month or of your neighbor's house, instantly, then click here.
I have expanded my knowledge base and now offer mortgages as well. For more information, please visit https://stevemilford.kellyrightrealestate.com/resources/mortgages
Everyone wants rates to come down before they buy, but we in the industry know that when that happens, all the pent demand is going to push prices up fast.
PLEASE NOTE: The rate you pay is ALWAYS a case-by-case scenario. What you see online is almost NEVER the true APR you pay. Rate = rate. APR = all the fees included and represented as a % (the true cost of the loan). The amount of people I meet that tell me, "I don't know how it works, but my guy gets it done" cracks me up. Few are paying attention to their APR, instead focusing on the rate. Look, I can get you any rate you want within reason, at a cost.
I was watching an interesting webinar recently that stated that the average consumer obtains 11 mortgages in their lifetime with all the refinancing that happens as people's scenarios change. To me, buy right first and win right now.
In every scenario, there are different lender overlays depending on the down payment, credit score, type of loan, use of loan funds, and fee to the lender (some charge less, some charge more).
This is the teeter totter world of lending, down payment vs. payment amount, complicated by closing costs. Be aware, additional fees are Processing fees and Underwriting fees usually average about $1,000 each. Lender fees if paid by the lender average 2.75% of the loan. If the lender fees are paid by the borrower, as a closing cost, they average 1.5%-2.75% or more. Go through me, my brokerage charges an average of 1.5% or less, and my brokerage caps these fees to protect the borrower as well.
In the following scenario, this is the best pricing scenarios I found today, 4/20/2024, 12pm PST, for a primary residence owner-occupied loan with the initial criteria for a first time home home buyer, 741 credit score, $450,000 loan, 3.5% down, WITHOUT the underwriting fee, processing fee, or lender fees, and does NOT include taxes. Plus we are going to finance the mortgage insurance premium and it is considered that the borrower is NOT financing the cost from the lender (my lender charges 1.5% on average) into the loan. (SIDE NOTE: this is cheaper versus lender financing lender fees)
FHA:
Rate = 6.245%
Principal & Interest = $2,719.11
Mortgage Insurance = $197.97
Total payment before taxes = $2,917.08
Conventional:
Rate = 6.942%
Principal & Interest = $2,872.18
Mortgage Insurance = $130.28
Total payment before taxes = $3,002.46
Let's say we change the scenario such that we received a gift of $15,000 from a family member to help with the down payment (essentially making the down payment 6.8%), and we also rolled $10,000 of closing costs into the loan. To keep it simpler, we did not change the purchase price:
FHA:
Rate = 7.250%
Principal & Interest = $2,922.12
Mortgage Insurance = $173.82
Total payment before taxes = $3,084.94
Conventional:
Rate = 7.916%
Principal & Interest = $3,153.24
Mortgage Insurance = $101.36
Total payment before taxes = $3,154.24
Analysis: As the scenario changed to higher down payment, the morgage insurance decreased, but the rate went up because we essentially asked for a credit from the lender of $10,000 for costs we were asking them to finance. In total the difference of using amounts in different spots results in an additional payment of $155+/-.
Let's run the same scenarios requests as if the Lender finances their fees in the loan.
This with a lower down payment, no gift, and no financing of closing costs.
FHA:
Rate = 8.177%
Total payment before taxes = $3,495.13
Conventional:
Rate = 8.060%
Total payment before taxes = $3,334.83
Again we change the scenario to get a gift of $15,000 to add to our down payment and see if we can finance $10,000 of closing costs.
HOMEREADY (like FHA, but different):
Rate = 8.625%
Total payment before taxes = $3,359.91
Maximum credit available to be used by borrower for costs = $4,051.40. (This is because a lot of the credit gets used to pay the lender fees)
Conventional:
Rate = 8.625%
Total payment before taxes = $3,363.41
Maximum credit available to be used by borrower for costs = $4,261.10. (This is because a lot of the credit gets used to pay the lender fees.)
Let me know how I can help you!
Feel free to share this with others. Want to get notified of new updates by email? Click here to receive notifications.
Hello, I'm Steve Milford, and I look forward to meeting and working with you. My perspective is a little bit different. I didn't become a Realtor for a job, I starting this journey because I like to f....
Here’s a collection of last month’s sales data for the areas served by RMLS. I hope you find it helpful.Want to get notified of new updates by email? Click here to subscribe!Please note,
Here’s a collection of last month’s sales data for the areas served by RMLS. I hope you find it helpful.Want to get notified of new updates by email? Click here to subscribe!Please note,
January's Jobs Report warrants a closer look, inflation data was encouraging, and existing home sales slowed to start the year. Here's a look at the key highlights.Headline Jobs Number Strong, But
Here’s a collection of last month’s sales data for the areas served by RMLS. I hope you find it helpful.Want to get notified of new updates by email? Click here to subscribe!Please note,
 All information provided is deemed reliable but is not guaranteed and should be independently verified. IDX information is provided exclusively for consumers' personal, non-commercial use, that it may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing, and that the data is deemed reliable but is not guaranteed accurate by RMLSTM.
The content relating to real estate for sale on this web site comes in part from the IDX program of the RMLSTM of Portland, Oregon. Real estate listings held by brokerage firms other than Kelly Right Real Estate are marked with the RMLSTM logo, and detailed information about these properties includes the names of the listing brokers. Listing content is copyright © 2026 RMLSTM, Portland, Oregon.
This content last updated on September 22, 2026 7:28 PM UTC at 4 AM. Some properties which appear for sale on this web site may subsequently have sold or may no longer be available.
 Southern Oregon Multiple Listing Service All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be
interested in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than Kelly Right Real Estate may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 22, 2026 7:46 PM UTC
Show More...
 All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. The data relating
to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than Kelly Right Real Estate may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 22, 2026 7:54 PM UTC
Show More...
