
Here’s a collection of last month’s sales data for the areas served by RMLS. I hope you find it helpful.Want to get notified of new updates by email? Click here to subscribe!Please note,

Dated: December 7 2024
Views: 38
Here is a bunch of data from last month regarding sales, where the RMLS serves. I hope this info helps you.
Want to get notified of new updates by email? Click here to subscribe!
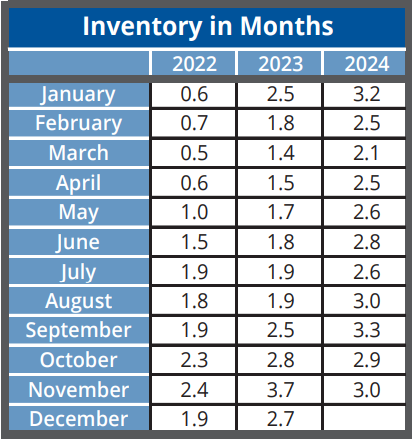
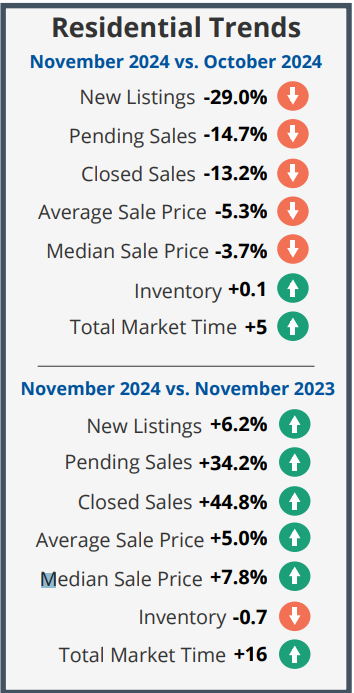
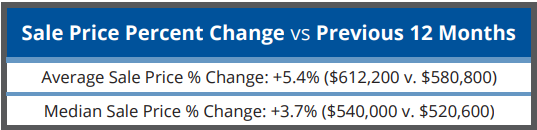
Please note, the arrows in the trends table only showcase numbers going up or down - NOT whether or not the trend is beneficial, as this is determined based on perspective.
Each area is stagnant in their own way. For example, one area might have prices staying the same but DOM are going up and inventory is the same.
SW Washington Report (Clark & Cowlitz) (click here to read report)
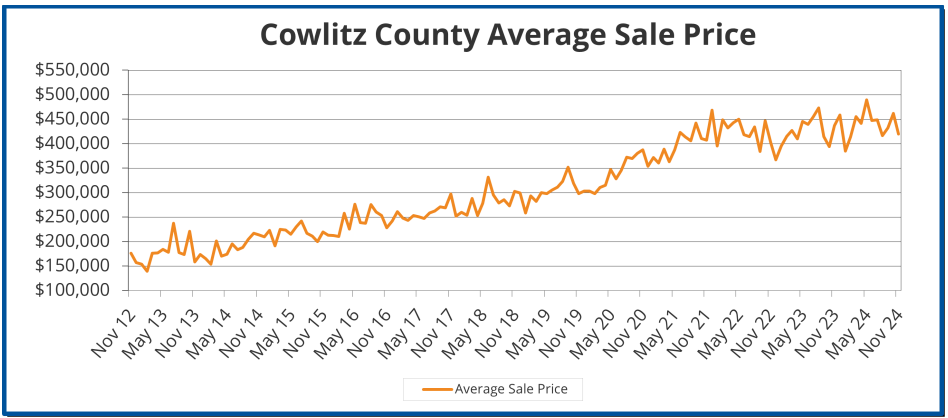
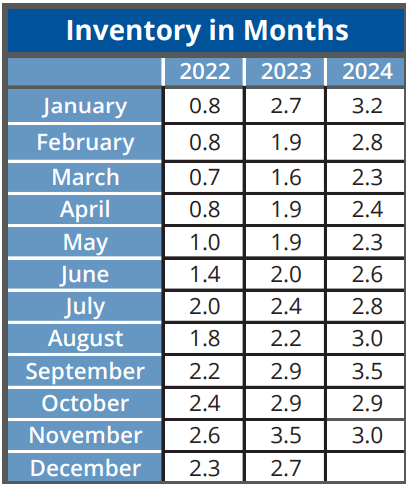
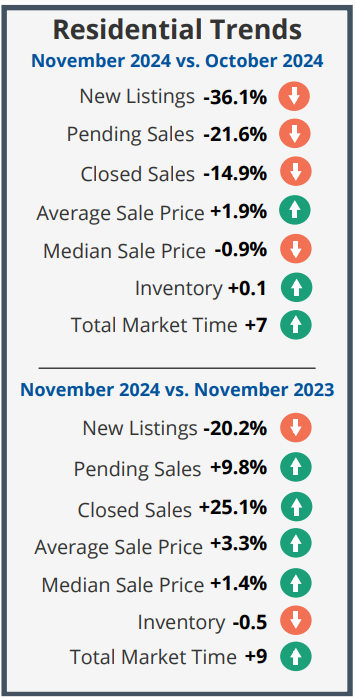
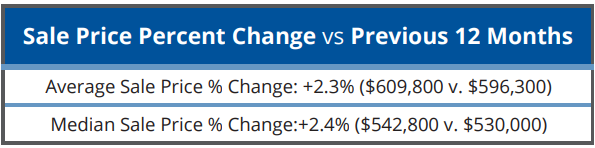
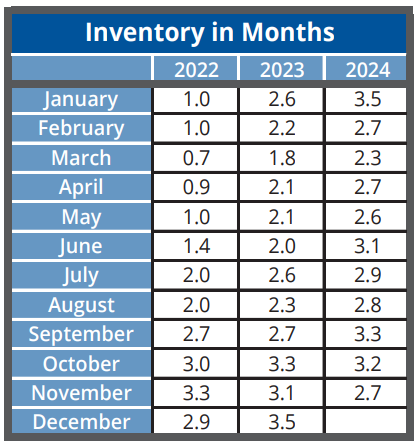
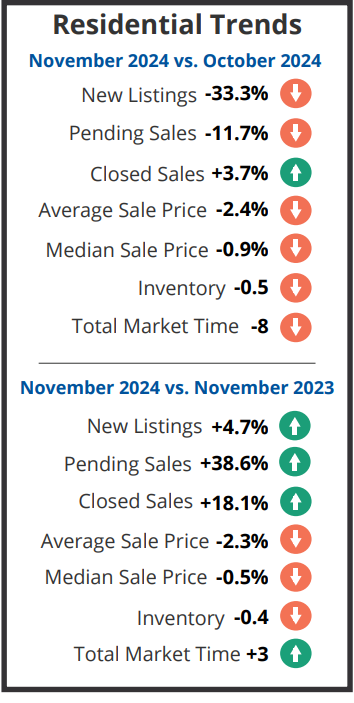
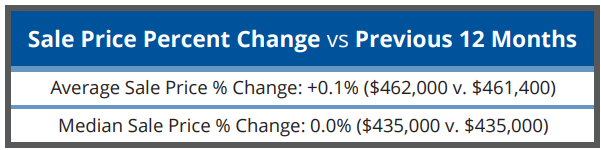
If you would like to see any other reports for Baker County, Columbia Basin, Coos County, Curry County, Douglas County, Grant County, Josephine County, Lane County, Mid-Columbia, North Coastal Counties, Union County, or Wallowa County, please give me a shout, and I can send them to you.
Another insightful tool to view areas include Altos Reports:
Click here for the report of Vancouver, WA 98682. Once this loads you can enter another zip code to see that area. Very insightful.
Some market snapshots:
Homes priced BELOW $400,000 in SW Washington. Click here to see that info.
Homes priced BELOW $400,000 south of the Columbia River. Click here to see that info.
FAIRVIEW VILLAGE, WA is an anomaly in the area, holding prices higher. This is a 55+ community. Click here to see the info.
LONGVIEW / KELSO area is still attractive for families looking for starter homes. Click here to see that info.
PORTLAND-METRO & SW WASHINGTON single-family homes with at least 3 bedrooms, 1.5 baths, at least 0.75 acres, and a maximum of $850,000. Click here to see that info.
To get your home value and a market report sent to your email each month or of your neighbor's house, instantly, then click here.
Rates are mixed (some days they are up and some days they are down) versus what they were at the publishing of last month's report.
This is Modus Mortgages' (the company I am affiliated with; owned by Kelly Right International) rate as of 12/2/2024 (see below). Remember this scenario is based on a 5% down and that every scenario is different, as every buyer is different. Let me know if you need a rate quote.
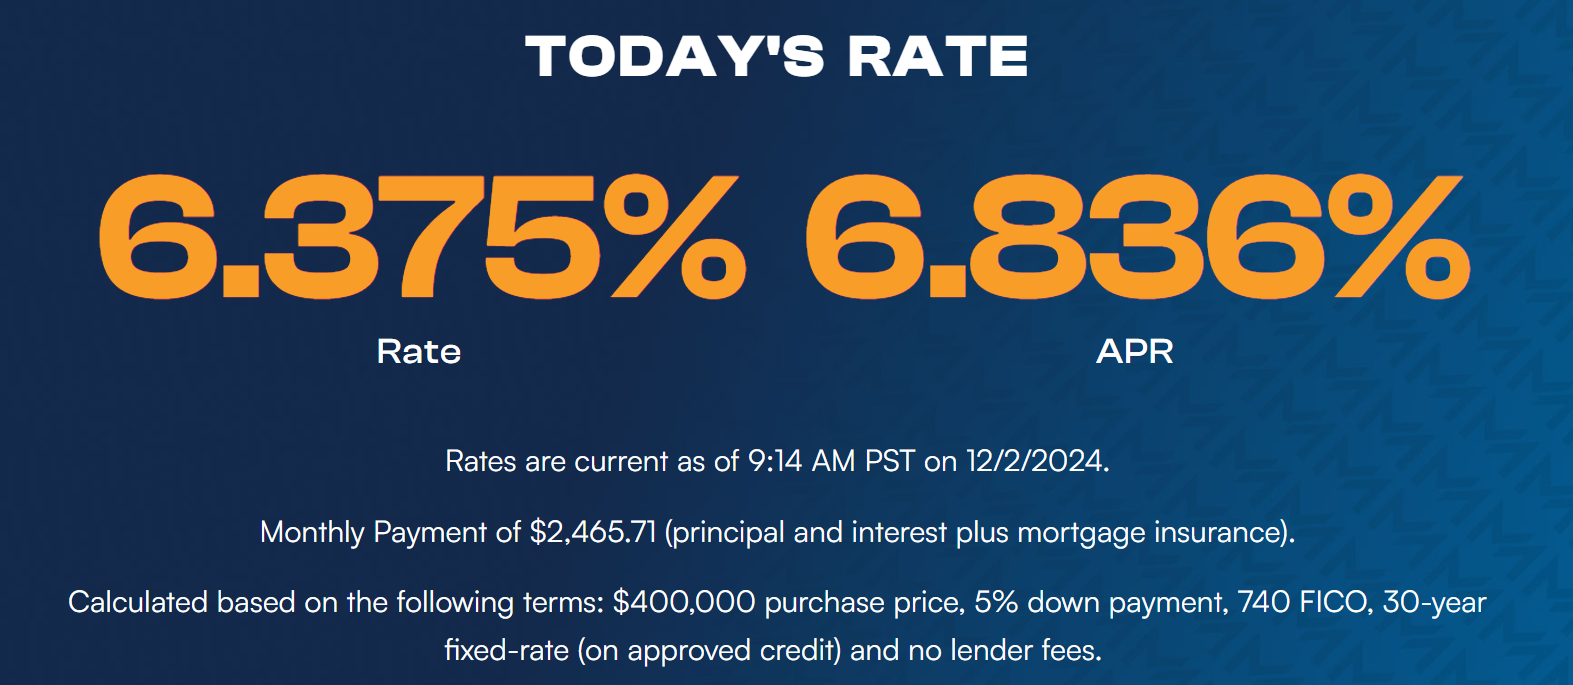
Somthing Buyers should know --> The "par rate".
A "par rate" in mortgages refers to the standard interest rate a lender will charge a borrower for a specific loan product, without any additional adjustments like discount points or lender credits; essentially, it's the baseline rate you qualify for without paying extra fees to lower the interest rate further, nor accepting a higher rate with a credit from the lender.
Key points about the par rate:
No points or credits:
When you receive a par rate, you are not paying any discount points upfront to lower your interest rate, nor are you receiving any lender credits that might slightly increase your rate. Note though, that few rates are quoted eactly at par. Most of the time they are quoted as being as near to par as possible. You will see what I mean below.
Comparison tool:
The par rate acts as a reference point to compare mortgage offers from different lenders as it allows you to see the base rate without any additional incentives or costs.
Factors affecting par rate:
A lender will determine your par rate based on factors like your credit score, loan type, and current market conditions.
Here is something to know - every lending firm that brokers loans takes the par rate and adjusts it for their fees, overhead including the origination fee. Some companies charge less and some charge more. No different than your landscaper - prices are different. That is why it makes sense to shop. And these adjustments happen every business day, often multiple times per day.
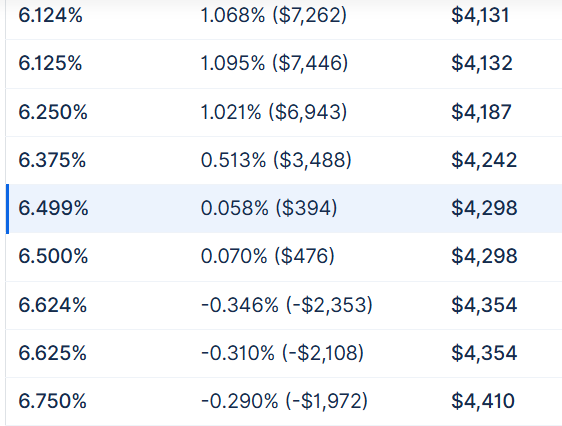
Take a look at this snapshot. This is based on an $850,000 purchase price, 20% down on a primary residence, with a Buyer with a 820 credit score, for a conventional mortgage. (FHA is a different animal with different rates.) I just ran this scenario in preparation to this blog. How does one read this?
The blue highlighted line is the rate closest to par. The first number in the row is the base rate, the next number is the cost in rate (Positive is the purchase cost in % and in $; negative is a lender credit in % and in $. Positive #s cost a Buyer money, and negative #s are a lender credit). The next number is the principal and interest combiled (not including insurance or taxes) of that rate. Now, the adjustment cost is based on the wholesaler promotions that are currently running and other fee adjustments.
SCENARIO 1:
So I next ran the same scenario, but pulled the cost from a different wholesaler. Take a look of this...the blue bar is the "closest to par rate", but if I wanted the same rate and mortgage payment of scenario #1, to "obtain" that rate, the Buyer would have to pay $4,348 extra to obtain that same rate (see yellow squiggly highlighter below).
SCENARIO 2:
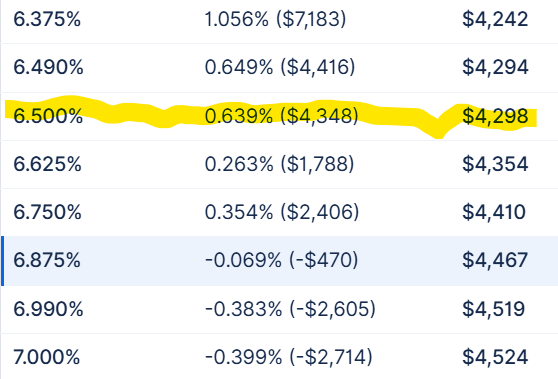
Same scenario for both, no changes - just different wholesalers.
Now you want to do something fun? Google the "national average mortgage rate today." That is what I did, and here is what I received...
"As of December 7, 2024, the national average interest rate for a 30-year fixed mortgage is 6.78%."
Loan Officers are trained to say, "just Google the rate and you will see I offer a better deal." Interesting. How about, did you know that if you pay for some of the "overhead" costs out of pocket that the rate can get even cheaper, which pushes down the principal and interest payment?
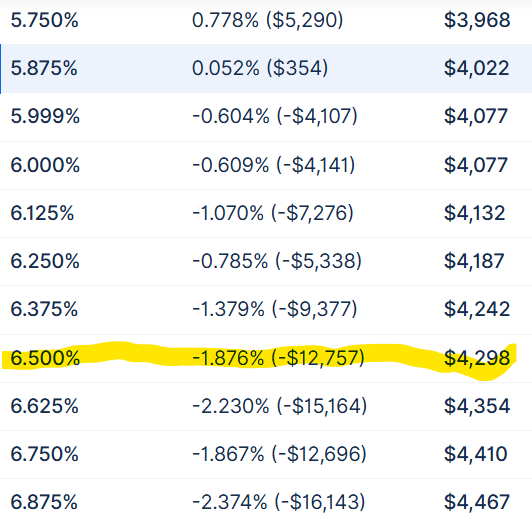
Check this out...Senario 3. Same scenario, basic details as above, except now some overhead costs the lender charges are paid for out of pocket versus paid for by the rate also known as not "baked into the rate". This only makes sense when someone has the cash to cover these fees. But for info, the par rate is 5.875% for a payment of $4,022. But to actually pay $4,298 in their payment, like in scenario 1, they would also receive a lender credit of $12,757 (see squiggly yellow).
These are just some of the nuances of mortgages, and only two variables of MANY that can be flexed. Feel free to call me if you want to have a discussion about rates and where we can push them to your advantage. Have a scenario you want to discuss, or need clarity? Or if you want an apples-to-apples comparison, give me a call, let's sort it out. NMLS# 2511040 1028232
Have a stellar day!
Hello, I'm Steve Milford, and I look forward to meeting and working with you. My perspective is a little bit different. I didn't become a Realtor for a job, I starting this journey because I like to f....
Here’s a collection of last month’s sales data for the areas served by RMLS. I hope you find it helpful.Want to get notified of new updates by email? Click here to subscribe!Please note,
Here’s a collection of last month’s sales data for the areas served by RMLS. I hope you find it helpful.Want to get notified of new updates by email? Click here to subscribe!Please note,
January's Jobs Report warrants a closer look, inflation data was encouraging, and existing home sales slowed to start the year. Here's a look at the key highlights.Headline Jobs Number Strong, But
Here’s a collection of last month’s sales data for the areas served by RMLS. I hope you find it helpful.Want to get notified of new updates by email? Click here to subscribe!Please note,
 All information provided is deemed reliable but is not guaranteed and should be independently verified. IDX information is provided exclusively for consumers' personal, non-commercial use, that it may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing, and that the data is deemed reliable but is not guaranteed accurate by RMLSTM.
The content relating to real estate for sale on this web site comes in part from the IDX program of the RMLSTM of Portland, Oregon. Real estate listings held by brokerage firms other than Kelly Right Real Estate are marked with the RMLSTM logo, and detailed information about these properties includes the names of the listing brokers. Listing content is copyright © 2026 RMLSTM, Portland, Oregon.
This content last updated on September 22, 2026 7:28 PM UTC at 4 AM. Some properties which appear for sale on this web site may subsequently have sold or may no longer be available.
 Southern Oregon Multiple Listing Service All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be
interested in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than Kelly Right Real Estate may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 22, 2026 7:46 PM UTC
Show More...
 All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. The data relating
to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than Kelly Right Real Estate may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 22, 2026 7:54 PM UTC
Show More...
